Adult Skills Made Simple: Budget, Communicate, Manage Life
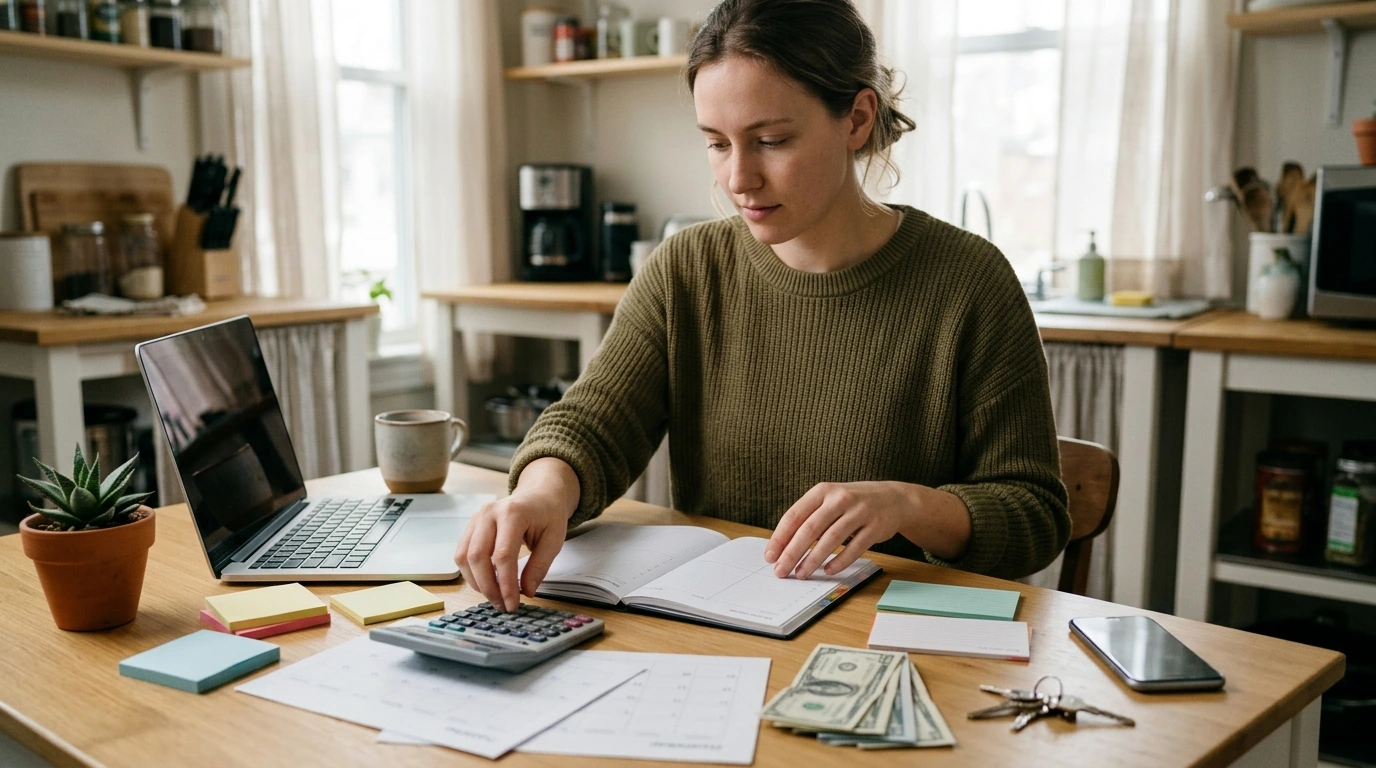
Essential Adult Skills for Everyday Success: Budgeting, Communication, Media Literacy, and Life Management
Adulting gets easier with a small set of repeatable skills: keeping money predictable, communicating clearly, filtering information wisely, and running day-to-day life with simple systems. The goal isn’t perfection—it’s fewer surprises, fewer last-minute scrambles, and more confidence when something changes. Below is a practical toolkit you can start today and strengthen week by week.
A simple “adult skills” toolkit that covers most real-life problems
Most everyday problems fall into four buckets. When you build a basic routine for each one, your life gets noticeably calmer:
- Money basics: track spending, plan bills, build buffers, and reduce financial surprises.
- Communication basics: set expectations, ask good questions, and handle conflict without escalating it.
- Media literacy basics: verify before sharing, recognize manipulation, and keep attention under control.
- Life management basics: calendars, habits, checklists, and decision rules that reduce stress and missed deadlines.
The fastest progress usually comes from layering skills: stabilize essentials first (bills and scheduling), then optimize (goals, growth, and big projects).
Budgeting that actually holds up: bills, spending, and savings
A budget fails when it’s too complicated or too fragile. Keep it simple and “bills-first” so the basics stay covered even when the month gets weird.
Step 1: Do a 30-minute money snapshot
- List monthly bills and due dates (rent, utilities, insurance, subscriptions).
- Write minimum debt payments (student loans, credit cards).
- Estimate average spending on food and transportation from recent transactions.
Step 2: Build a “bills first” structure
- Match bills to income dates so you know what must be paid from each paycheck.
- Schedule payments and keep a small checking buffer to avoid overdrafts.
- Automate recurring transfers to savings if possible.
Step 3: Pick one method for 30 days
- Zero-based: every dollar has a job (bills, groceries, savings, fun).
- Simple split: needs/wants/savings with a few core categories.
Choose one and run it for a month before changing it. Consistency beats constant redesign.
Step 4: Prevent budget drift
Most budgets “leak” in the same places. Set 1–2 category caps where spending usually blows up—often takeout, subscriptions, or rideshares. If you only fix those, your budget will feel more real.
Quick Budget Setup (Example Categories)
| Category | What it includes | How to set a starting number |
|---|---|---|
| Bills & essentials | Rent/mortgage, utilities, insurance, minimum debt payments | Use statements and due dates; start with actual totals |
| Food | Groceries + occasional meals out | Estimate last month; cap takeout first |
| Transport | Fuel, transit pass, maintenance, parking | Average last 2–3 months |
| Health & personal | Prescriptions, copays, toiletries | Use typical month; add buffer for irregular costs |
| Savings buffer | Emergency fund and sinking funds (car, gifts) | Start small and automate; increase after two pay cycles |
For additional budgeting tools and plain-language guidance, the Consumer Financial Protection Bureau (CFPB) budgeting resources are a solid reference.
Communication skills that reduce friction at work and at home
Clear communication is a stress reducer. It prevents mismatched expectations and lowers the chance that a small issue turns into a bigger one.
Use clear requests
Make requests that include the outcome, deadline, and constraints. Example: “Can you send the updated draft by Thursday at 3 PM? It doesn’t need final polish—just the key numbers.”
Confirm understanding
Close the loop with one sentence: “So the plan is X by Friday, and I’ll handle Y today—did I miss anything?” This prevents silent confusion.
Handle conflict with a structure
- Describe facts (observable, specific).
- Share impact (how it affected time, money, or trust).
- Ask for a solution (a specific change).
- Agree on next steps and a timeline.
Set boundaries without overexplaining
Try: “I can do X by Friday, or Y by Wednesday—choose one.” This keeps things respectful while staying realistic.
Media literacy for everyday decisions (news, social, AI, and scams)
Information comes fast, and not all of it is designed to help you. A few habits protect your money, your time, and your judgment.
Pause before sharing
Outrage, fear, and “instant victory” stories are common manipulation triggers. If something makes you feel an immediate rush, treat it like a yellow light.
Check the source and the date
Verify the publisher, author, and when it was posted. Then see whether other credible outlets confirm it. Stanford’s research-backed approach to online evaluation is worth reviewing via Civic Online Reasoning.
Separate claims from evidence
Protect attention like a resource
For scam awareness and practical examples, the Federal Trade Commission (FTC) scam guidance is a reliable place to start.
Life management systems: the calendar, the checklist, and the weekly reset
Run life from one calendar
Use a capture list for everything else
Create three reusable checklists
Do a weekly reset (20–30 minutes)
A 14-day skill-building plan that doesn’t require motivation
Using a structured guide to stay consistent
- Essential Adult Skills Guide | Budgeting, Communication, Media Literacy & Life Management Tips for Everyday Success
- Finally Focused: The Anti-Procrastination Workbook – Productivity Ebook & Focus-Building Guide with Time Management Tools
- First-Time Parent Survival Guide – Newborn Care, Sleep Tips, Emotional Support & Parenting Strategies Digital Download
FAQ
What is the easiest way to start budgeting without feeling overwhelmed?
Start with one month of real numbers: list fixed bills and estimate 3–5 spending categories from recent transactions. Add one small automated savings transfer, then adjust after two pay cycles based on what actually happened.
How can misinformation be spotted quickly on social media?
Check the original source, date, and whether credible outlets corroborate the claim. Watch for emotional framing, screenshots without context, and posts that don’t provide primary evidence.
What should be said during a difficult conversation to avoid escalation?
State observable facts, describe the impact, ask for a specific change, and confirm the next step with a timeline. Keeping the focus on a solution prevents the conversation from turning into a blame cycle.

Leave a comment