Personal Finance Reset: Budget, Save, Invest, Kill Debt
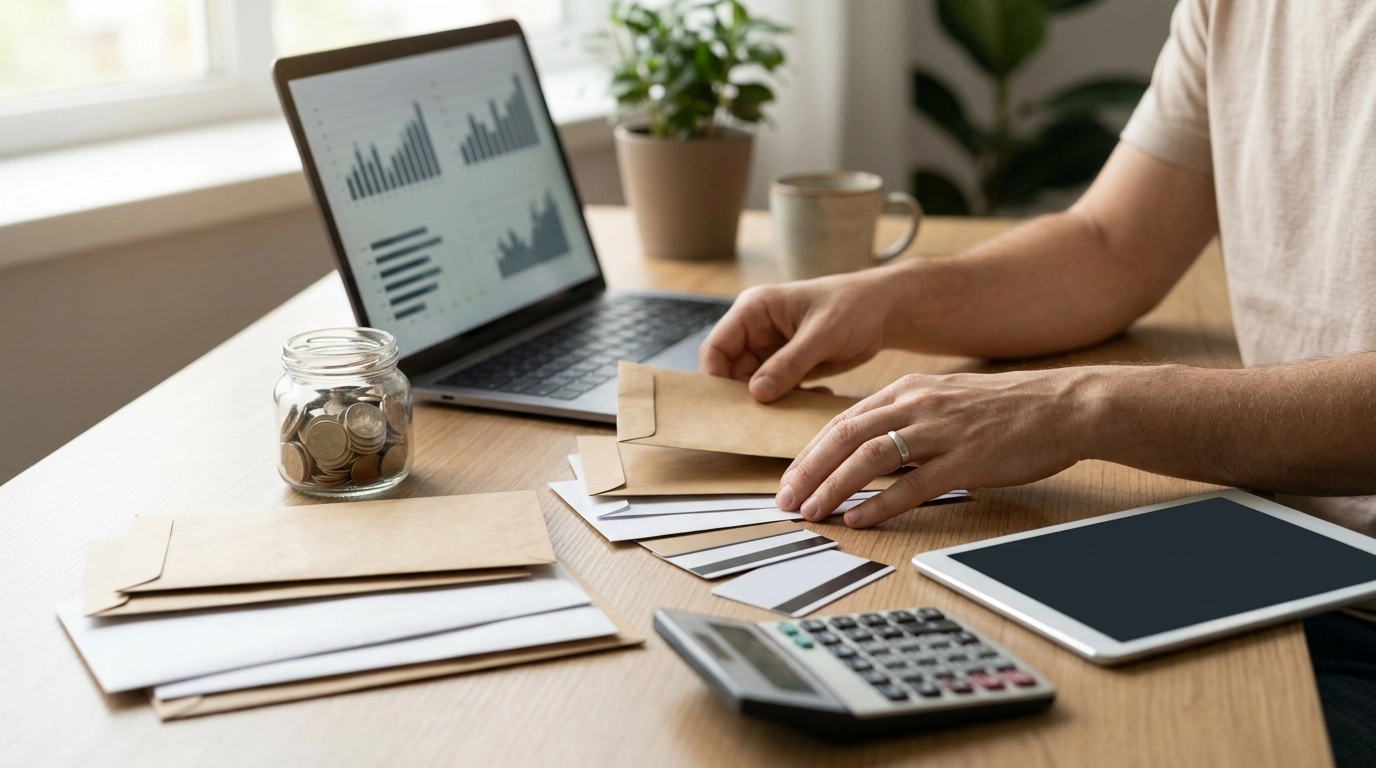
Personal Finance Made Easy: A Practical Path to Budgeting, Saving, Investing, and Debt Freedom
Building financial freedom becomes simpler when money decisions follow a clear system: know where cash goes, create a plan that fits real life, protect an emergency buffer, invest with purpose, and eliminate high-cost debt. The goal isn’t perfection—it’s a repeatable routine that keeps bills paid, reduces stress, and steadily increases options over time. Below is a practical framework you can start today, plus a structured resource that helps turn good intentions into consistent habits.
What “financial freedom” looks like in everyday life
Financial freedom is less about a single number and more about having choices. It can look like covering essentials without anxiety, handling a surprise car repair without panic, and saying yes to important goals (a move, a class, a family trip) without going into debt.
Measurable milestones make progress visible: a starter emergency fund, steady debt payoff, consistent investing, and cash flow that doesn’t rely on credit cards to bridge the month. It also helps to separate short-term stability (cash reserves for life’s messiness) from long-term wealth building (investments designed to grow over years).
Most people get stuck at the same friction points: impulse spending, irregular income, high-interest debt, and a vague plan that’s hard to follow on busy weeks. Solving those bottlenecks—one at a time—creates momentum.
Start with a simple snapshot: income, expenses, and net worth
A clear snapshot reduces overwhelm because it replaces guessing with facts. Start by listing every income source and how it arrives: weekly, biweekly, monthly, or variable (side gigs, commissions, seasonal work). Then track expenses in broad categories first—fine details can come later.
- Housing (rent/mortgage, insurance)
- Transportation (gas, repairs, payments)
- Food (groceries, dining out)
- Utilities (electric, water, internet, phone)
- Subscriptions (streaming, apps, memberships)
- Debt (credit cards, student loans, personal loans)
- Discretionary (shopping, hobbies, entertainment)
Next, calculate net worth: assets (cash, retirement, investments) minus liabilities (credit cards and loans). Don’t judge the number—use it as your starting point. Finally, pick one tracking method you can sustain: a spreadsheet, an app, or envelope-style digital categories. To keep it manageable, set one priority goal for the next 30 days (for example: stop overdrafts, build a $500 buffer, or pay off one small card).
Budgeting that works: choose a style and make it realistic
Common budgeting methods and when they fit best
| Method | How it works | Best for | Watch-outs |
|---|---|---|---|
| 50/30/20 | Allocate income to needs, wants, and goals/savings | Beginners who want a quick structure | May be too loose for high debt or tight margins |
| Zero-based | Assign every dollar a job before the month starts | People who want control and clarity | Requires regular check-ins to stay accurate |
| Envelope/categories | Limit spending by category caps (cash or digital) | Overspenders needing firm boundaries | Can be inconvenient without digital tools |
| Paycheck budgeting | Plan spending around each pay period | Variable income or biweekly pay schedules | Needs good calendar tracking of due dates |
Saving made automatic: emergency fund, sinking funds, and goal-based savings
For additional budgeting and money management tools, the Consumer Financial Protection Bureau (CFPB) budgeting resources offer practical guidance and calculators.
Debt management that reduces interest and stress
As a safeguard, reduce new debt while paying down: tighten a few spending categories, pause nonessential subscriptions, and rely on a written plan rather than willpower. The Federal Trade Commission (FTC) guide to getting out of debt is a helpful reference for evaluating options.
Investing fundamentals: start simple and stay consistent
Focus on diversification and low costs, and avoid chasing short-term performance. Choose a contribution target that fits your life even during expensive seasons. Match the investment approach to the timeline: short-term goals generally need safer options than long-term retirement planning. Rebalance occasionally, but avoid frequent trading that increases stress and taxes. For an overview of core concepts, review SEC Investor.gov investing basics.
A 30-day reset plan to build momentum
Using a structured guide to stay consistent
Format matters, too: quick chapters, practical examples, and repeatable templates make it easier to follow through during busy weeks. If procrastination and follow-through are the main obstacles, pairing a money plan with productivity structure can help. The Finally Focused: The Anti-Procrastination Workbook – Productivity Ebook & Focus-Building Guide with Time Management Tools is a strong companion for building the weekly review habit that keeps financial progress on track.
Recommended ebook for a clear, all-in-one money system
For a single organized framework (instead of piecing together advice from multiple sources), Personal Finance Made Easy Ebook – Budgeting, Saving, Investing & Debt Management Guide for Financial Freedom is designed as a practical roadmap for building stability and long-term growth. Used alongside a short weekly check-in, it helps translate goals into repeatable actions—so budgeting, saving, investing, and debt payoff support each other rather than competing for attention.
FAQ
What’s the best order: save, pay off debt, or invest?
Cover minimums on all debts first, then build a starter emergency fund to reduce the chance of taking on new debt. After that, focus on high-interest payoff while contributing to investing if you have a strong employer match or a long timeline.
How much should go into an emergency fund?
Start with a small buffer (often $500–$1,000), then build toward 3–6 months of essential expenses. The right target depends on income stability, household needs, and how easily expenses can be reduced in a pinch.
Is the snowball or avalanche method better for paying off debt?
The avalanche method saves the most interest by prioritizing the highest APR, while the snowball method can improve consistency by creating quick wins. The better method is the one you’ll stick with every month until the balances are gone.

Leave a comment